
Crowdfunding has opened up access for individuals to alternative investments that were previously reserved for a narrower circle of investors. Among the players in this market, Afranga allows individuals to invest in different types of projects and companies, aiming for attractive returns in exchange for higher risk of capital loss.
Afranga offers two main ways to invest. Investors can opt for SaveSmart, a fixed-term automated solution, or select their investments themselves from the Afranga Marketplace.
But who is Afranga? What investments are accessible and what returns does Afranga offer? What are Afranga’s 2026 fees? And what are the risks and advantages of the Afranga platform?
Discover our Afranga 2026 review. Our analysis of its offering will help you understand how it works before considering investing.
Afranga, what is it? History & Key Figures 2026
Founded in 2021, Afranga is a European crowdfunding platform based in Sofia, Bulgaria. Its principle is fairly simple: allow individuals to finance companies through loans and, in return, collect interest on the invested sums. This placement is not without risk since the invested capital can be lost. Since September 2023, Afranga has held the status of a European crowdfunding service provider (ECSP/PSFP), with authorization granted by the Bulgarian Financial Supervisory Commission (FSC Resolution 863/12.09.2023).
As of July 31, 2026, €40.23 million had been invested via Afranga. The platform then counted 7,484 investors and had already paid out €2.86 million in interest. To offer its various investments, Afranga relies notably on several European lending companies.
Some key figures concerning Afranga
Afranga Review: How Good Is Afranga’s Offer?
To invest with Afranga, two possibilities are available to you. You can :
- choose SaveSmart if you prefer automated management of your investments,
- go through the Marketplace to directly select the opportunities that interest you,
We will now detail these two fairly different approaches.
Afranga Marketplace: choosing your investments yourself
The Marketplace is the most flexible solution offered by Afranga. For more experienced investors, the Marketplace allows access to opportunities offering returns of up to 16% per year. Performance is not guaranteed and there is a high risk of principal loss.
Unlike SaveSmart, which we will examine shortly, there is no automatic allocation: the investor reviews the opportunities available on the platform and selects those in which they want to invest.
These include business loans, consumer loans, or asset-backed financings, offered by various credit institutions partnering with Afranga.
For each opportunity, several pieces of information are available to help you decide:
- Interest rate
- Loan term
- Available amount
- Loan repayment schedule
- Borrower/originating company
It is thus possible to spread your money across several investments rather than putting everything into a single loan.
This freedom, however, requires more involvement: it is up to the investor to select their placements and to evaluate the level of risk they are willing to accept.
SaveSmart Afranga: investing automatically
With SaveSmart, Afranga offers a solution for those who do not wish to select loans themselves. The investor chooses the amount they want to invest, and Afranga then handles the allocation of the funds.
The goal is to simplify investing by letting Afranga guide the allocation of funds without having to select each loan yourself. It is possible to invest from €10 per month.
Afranga also provides a simulator allowing you to project over 5, 10, 15 or 20 years. We tested it with €150 deposited each month for 10 years and an assumed annual return of 10%. The simulator estimates that the savings would reach €3,967 after two years, then €30,727 after 10 years. During that period, the investor would have paid in €18,000, to which €12,727 of potential gains would be added.
SaveSmart Simulation by Afranga
However, it is important to understand that this is a projection and not a promise of return. SaveSmart remains an investment in private loans, with a high risk of capital loss. The invested amounts do not benefit from bank deposit guarantees. Actual results may therefore differ from those shown by the simulator.
With SaveSmart, the investor can choose between several investment durations with a known interest rate in advance. Three maturities are offered: 3 months at 8% per year, 6 months at 9% or 12 months at 10%. Interest is paid monthly and the principal is repaid at maturity. Again, this is not a capital-guaranteed placement: the investment remains exposed to a high risk of capital loss.
We ran a simulation with €10,000 invested for 12 months at the rate of 10%. Afranga thus estimates the interest at €1,000, for a total of €11,000 at maturity. In addition, there is currently a SaveSmart cashback offer of 2%, i.e., €200 extra in our example. Note that this cashback is a temporary promotional offer valid until September 30, 2026 and should not be included in the investment’s normal return.
Simulation with SaveSmart fixed rates
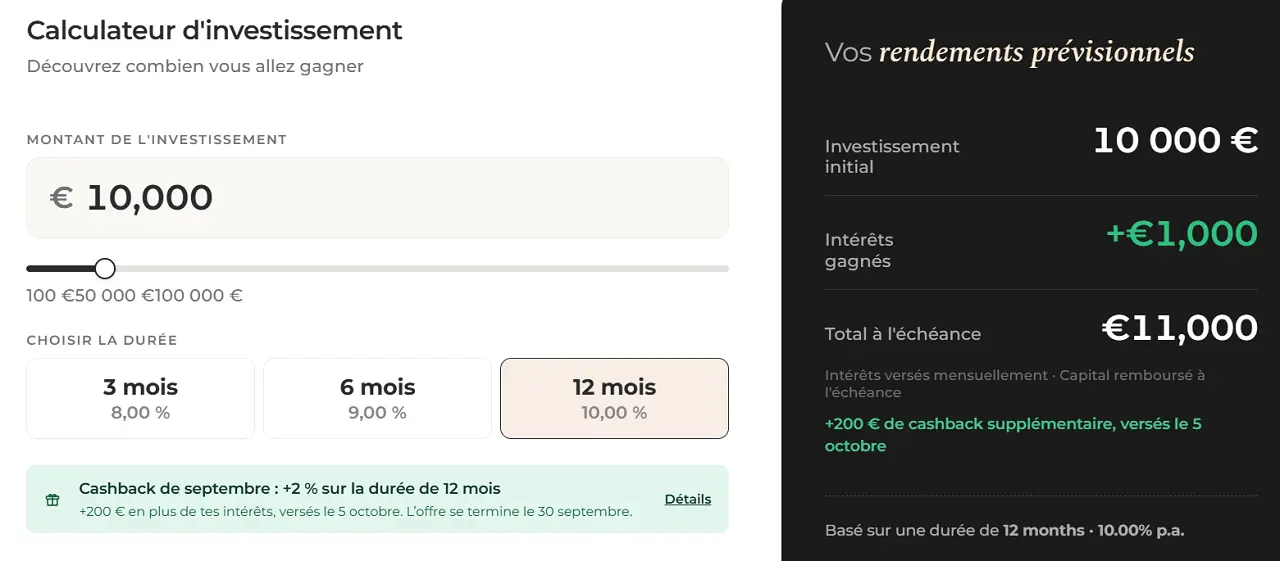
Be careful not to confuse fixed rate with guaranteed return. With SaveSmart, the interest rate is fixed and known from the start: the investor thus knows what rate will apply throughout the investment’s duration. However, the principal remains at risk and the actual payment of interest is not guaranteed. In the event of default or repayment difficulties, the investor may not receive all of the planned interest and may also lose all or part of the invested capital.
What are Afranga’s fees in 2026?
For investors, Afranga charges no platform fees: registration, account maintenance, and standard deposits and withdrawals are free.
Afranga acts as an intermediary between investors and the companies seeking funding. Its business model is therefore based on the services charged to borrowers rather than commissions taken from individual investors’ investments.
Note, however, there is an exception: with SaveSmart, an early withdrawal is charged 1% of the amount withdrawn.
Afranga Review: What are the Pros and Cons of Afranga?
Overall, Afranga’s offering seems quite comprehensive to us, notably due to the different ways to invest and the potentially attractive returns. As always with this type of investment, there are nonetheless drawbacks and, above all, risks to consider before investing.
What are the advantages of Afranga?
- Interest rates can reach up to 10% per year with SaveSmart and up to 16% per year on the Marketplace
- Ability to start investing with small amounts
- No platform fees for the investor
- Ability to choose investments yourself via the Marketplace
- An automated solution with SaveSmart for investors who want to spend little time on their investments
- European platform with PSFP status
What are the disadvantages of Afranga?
- Expected interest is not guaranteed, even when the rate is fixed in advance
- Investment that carries a high risk of capital loss
- Limited liquidity and variability depending on the chosen investment type
- 1% fee for early withdrawal with SaveSmart
- Need to carefully study borrowers and projects when investing directly via the Marketplace
Note: funds invested via Afranga are not covered by a deposit guarantee scheme. The invested capital is at risk and can be lost in whole or in part.
Afranga customer reviews
On Trustpilot, Afranga has a score of 3.2/5 from 37 reviews. This score, somewhat average at first glance, should be interpreted in light of the relatively small number of reviews published to date.
In detail, positive Afranga customer comments are fairly encouraging. Several investors particularly appreciate the platform’s ease of use, its intuitive interface, the returns offered, or the absence of fees to invest. Some Afranga customers also report satisfaction with the results achieved and their overall experience with Afranga.
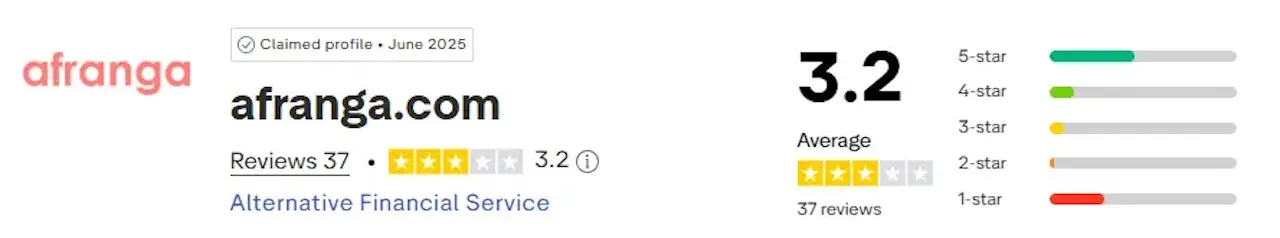
On the negative reviews side, a significant portion of recent criticism concerns more the referral program than the investments themselves, particularly bonuses that were not paid. Other users report difficulties related to bank account validation, withdrawals, or delays in Afranga’s customer service.
The 3.2/5 rating should thus be viewed in context: the critiques do not only concern the quality of Afranga’s investment offering. Indeed, several platform customers express strong satisfaction with their experience.
Afranga Review: Who Is Afranga’s Offering For?
The Afranga offering is primarily aimed at investors who want to diversify their placements outside traditional financial markets and who are willing to take on a higher risk of capital loss in exchange for potentially higher returns.
The platform can suit both beginners, thanks to SaveSmart and an investment accessible from €10, and more autonomous investors who wish to select their opportunities themselves on the Marketplace.
SaveSmart may also appeal to those seeking a fixed rate and a known duration in advance. Afranga should, however, remain a diversification investment because the price of potentially higher returns is a higher risk of loss.
Our View on Afranga
Our view of Afranga is overall positive.
The platform makes it easy to access investments offering potential returns higher than many traditional savings products, with multiple ways to invest according to your profile. We also appreciate the absence of fees for the investor and the fact that Afranga is a regulated player with PSFP status. Despite its young age, Afranga has already attracted several thousand investors and several tens of millions of euros in capital.
However, one should never lose sight of the level of risk. The displayed rates may be fixed and known in advance, but the capital and the actual payment of interest are not guaranteed.
For us, Afranga can thus find a place in a diversification strategy, provided you allocate a reasonable portion of your wealth to it.
How to open an Afranga account?
Opening an Afranga account is done entirely online and only requires a few steps. As Afranga is a regulated platform, registration includes an identity verification procedure before you can deposit money and start investing.
You will need to:
- create your Afranga account by providing your email address and the requested information;
- verify your identity by following the KYC procedure and submitting the necessary documents;
- validate your bank account in order to make deposits and future withdrawals;
- fund your Afranga account by bank transfer;
- choose your investment solution between the Marketplace and SaveSmart;
- select the amount you wish to invest, then confirm your first investment;
- monitor your placements and the interest earned directly from your Afranga personal space.
Once your account is funded, you will be able to make your first investment on Afranga and begin tracking its progress directly from your personal space.
Sponsored article
All of our information is, by nature, generic. It does not take into account your personal situation and does not constitute personalized recommendations for carrying out transactions and cannot be construed as financial investment advice, nor as any encouragement to buy or sell financial instruments. The reader is solely responsible for using the information provided, with no recourse against the publishing company Cafedelabourse.com. The publishing company’s liability cannot be engaged in case of error, omission, or unsuitable investment.
